How to Build an Emergency Fund on a Tight Budget
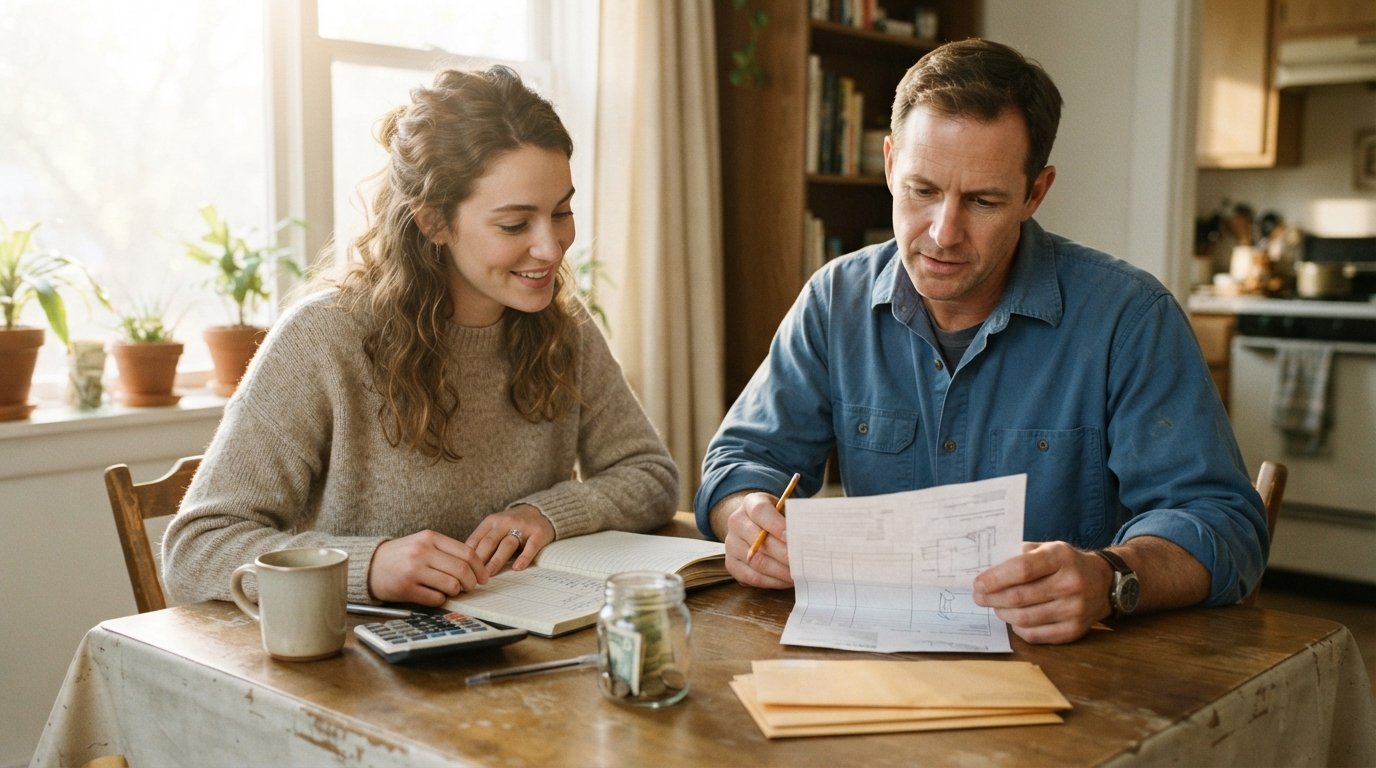
Building an emergency fund on a tight budget is possible with small, consistent steps. Start with a $200 goal and automate micro-transfers to build a safety net.
By Rania Barakat
Your car breaks down on a Tuesday morning. The repair estimate is $600, and your checking account holds $87 until Friday. This scenario plays out for millions of Americans every year, and it is exactly why an emergency fund matters. But when every dollar already has a job, saving feels impossible. The good news is that building a financial safety net does not require a windfall or a second income. It requires a realistic plan, small consistent actions, and a clear understanding of where to keep the money so it is available when you need it most. This guide walks you through how to build an emergency fund on a tight budget without sacrificing your current obligations or falling into debt.
Start With a Small, Achievable Target
The biggest mistake people make is aiming for three to six months of expenses right out of the gate. That target, while ideal, can feel so overwhelming that it paralyzes action. If you are living paycheck to paycheck, a $10,000 goal is not motivating; it is discouraging. Instead, start with a micro-goal that you can hit quickly. Financial experts often recommend a starter emergency fund of $500 to $1,000, but even that may be too steep for some budgets. Your first target should be one that you can reach within four to eight weeks.
Consider a $200 initial goal. That amount covers many common emergencies: a urgent prescription, a minor car repair, a utility bill spike, or a last-minute trip to the doctor. Once you hit $200, celebrate the win and set the next target at $500. Then aim for $1,000. Each milestone builds momentum and confidence. The psychological benefit of crossing a finish line, even a small one, is powerful. You are training your brain to see saving as something you do, not something you attempt.
Once you have $1,000 set aside, you can start working toward a more robust fund that covers one month of essential expenses. From there, you can gradually expand to three months if your budget allows. The key is to let your emergency fund grow in stages. Do not wait until you have a large sum to start; start where you are and let consistency do the heavy lifting.
Find Small Amounts to Save Each Pay Period
When your budget is tight, saving requires creativity and a willingness to examine every expense. The goal is not to eliminate all enjoyment from your life but to identify small leaks that can be redirected toward your emergency fund. Start by tracking your spending for two weeks. Use a notebook, a spreadsheet, or a free budgeting app. You will likely find at least a few areas where you can trim without feeling deprived.
Here are several practical strategies to find money to save each pay period:
- Automate a micro-transfer: Set up an automatic transfer of $10 or $20 from your checking to your savings account on payday. Because it happens before you see the money, you are less likely to miss it. Over a year, $20 per paycheck adds up to more than $500.
- Use the 50/30/20 rule as a guide, not a rule: If your needs consume 80% of your income, aim to save just 2% or 3% instead of the standard 20%. Small percentages still build the habit.
- Redirect temporary savings: When you finish paying off a small debt or a subscription you canceled, immediately route that same amount to your emergency fund. You were already used to living without it.
- Bank your windfalls: Tax refunds, birthday money, cash-back rewards, and side gig income are not part of your regular budget. Commit at least half of any unexpected money to your fund.
- Try a no-spend challenge: Pick one category, such as dining out or coffee, and pause it for two weeks. Put the money you would have spent directly into savings.
Another effective approach is to save physical cash. Some people find that keeping a small envelope of $5 and $10 bills feels more tangible and discourages impulse spending. However, cash is vulnerable to loss or theft. If you choose this route, keep it in a secure location and treat it as untouchable. For most people, a separate savings account at a different bank from your checking account provides the right balance of accessibility and friction. You can also use a round-up app that links to your debit card and invests or saves your spare change, but be mindful of any fees.
Remember that the amount matters less than the consistency. Saving $5 per week is $260 per year. That is a real cushion for a small emergency. The act of saving regularly rewires your financial habits and makes larger savings feel possible later.
Where to Keep Your Emergency Fund for Quick Access
Your emergency fund needs to be liquid, meaning you can access it within one to two business days without penalty. It should not be invested in stocks or locked into a long-term certificate of deposit. At the same time, it should not sit in your everyday checking account where you might accidentally spend it on non-emergencies.
A high-yield savings account (HYSA) is often the best choice. These accounts are offered by online banks and some credit unions, and they typically pay much higher interest than traditional savings accounts while remaining fully liquid. You can link the HYSA to your checking account for easy transfers. The separation creates a psychological barrier: you have to intentionally move money, which gives you a moment to ask yourself whether the expense is truly an emergency.
If you prefer a more traditional option, a standard savings account at your local bank works fine. The interest rate matters less than the habit. What is critical is that you do not keep the fund in a checking account tied to a debit card, and you do not use a retirement account or a home equity line of credit as your primary emergency fund. Those options come with penalties, taxes, or the risk of losing your home. Your emergency fund should be boring, safe, and separate.
Some people use a tiered approach: keep the first $500 in a savings account at the same bank as checking for instant access, and keep the rest in a higher-yield account that takes a day to transfer. This strategy balances convenience with a small return. Whatever you choose, make sure you can get the money quickly when you need it. A broken furnace in January does not wait for a three-day transfer window.
Position Short-Term Loans as a Bridge, Not a Substitute
Even with the best intentions, emergencies sometimes arrive before your fund is fully built. In those moments, a short-term loan can serve as a bridge to cover an urgent expense, but it is not a replacement for savings. Short-term loans, including payday loans and cash advances, are designed for temporary cash flow gaps. They can be useful if you know exactly how and when you will repay them, but they come with high fees and short repayment terms that can trap you in a cycle of debt if you are not careful.
If you are facing an immediate expense and your emergency fund is not yet sufficient, consider all your options before borrowing. Can you negotiate a payment plan with the service provider? Can you sell an unused item? Can you ask a family member for a short-term loan? If you do decide to explore short-term lending, use a connection service to compare offers from multiple lenders. One option is StartCashLoan, a free online connection service that helps U.S. consumers find short-term and payday loan options. Visitors complete one simple request form and may be matched with third-party lenders in the network. StartCashLoan is not a lender and does not make credit decisions; any loan terms come directly from the lender. The site also publishes plain-language guides on borrowing, budgeting, and repayment. Using a service like this can help you review multiple offers quickly, but always read the terms carefully and borrow only what you can repay on time.
The decision to borrow should be part of a broader plan. If you use a short-term loan to cover an emergency, make a commitment to rebuild your emergency fund as soon as the loan is repaid. Treat the loan as a one-time bridge, not a recurring solution. The goal is to eventually have enough saved so that you never need to borrow for a small or medium emergency again.
Build the Habit, Not Just the Balance
An emergency fund is not just a number in an account; it is a reflection of your financial habits. The process of saving small amounts regularly builds discipline and awareness. As you see your balance grow, you will likely feel more motivated to protect it. You might start to view unnecessary expenses differently, asking yourself whether a purchase is worth delaying your security.
One useful technique is to create a visual tracker. Draw a thermometer or a progress bar on a piece of paper and color it in as you save. Or use a digital goal tracker in your banking app. Seeing progress, even slow progress, reinforces the behavior. Another strategy is to name your savings account something meaningful, like "Peace of Mind" or "Car Repair Fund." This small act makes the money feel purposeful and harder to raid for impulse purchases.
Involve your household in the effort. If you have a partner or children, explain what you are doing and why. A family that saves together is more likely to succeed. You can make a game of finding small savings: who can find the best coupon, who can go the longest without a takeout meal, who can suggest the most creative free weekend activity. The goal is to normalize saving as a family value, not a punishment.
Finally, do not get discouraged by setbacks. You may need to use your emergency fund for an actual emergency, which is exactly what it is there for. Rebuilding after a withdrawal is part of the process. The important thing is to start again, even if you have to begin with $10. Consistency over time is what creates financial resilience.
Protect Your Fund From Everyday Temptation
Once you have a few hundred dollars in your emergency fund, the temptation to dip into it for non-emergencies can be strong. A sale on a new phone, a weekend trip, or a dinner out with friends can suddenly feel like an emergency if you are not careful. To protect your fund, establish a clear definition of what counts as an emergency. Write it down and keep it where you can see it. A good rule is that an emergency is an unexpected, necessary expense that cannot be postponed and cannot be covered by your regular monthly budget.
Examples include medical bills, car repairs, essential home repairs, and unexpected travel for a family emergency. Non-examples include holiday gifts, concert tickets, and a new wardrobe. If you are unsure, wait 24 hours before making a withdrawal. Often, the urgency fades. You can also create a separate "sinking fund" for planned irregular expenses like car maintenance or holidays. That way, those costs do not have to come out of your emergency fund.
Another protective measure is to set a withdrawal limit. For example, decide that you will not touch the fund for anything under $100 unless it is a true emergency. This reduces the number of small raids that can erode your savings. If you do need to withdraw, replace the money as soon as possible. Treat it like a loan to yourself, with a repayment plan.
When to Use a Short-Term Loan as a Bridge
Despite your best efforts, there may be times when an emergency outpaces your savings. In those cases, a short-term loan can provide a temporary bridge. The key is to use it responsibly. Before you apply, calculate exactly how much you need and how you will repay it. Do not borrow more than necessary, and do not accept a loan with terms you do not fully understand. Payday loans, for example, often carry annual percentage rates (APRs) that exceed 300%, and they are typically due on your next payday. If you cannot repay the full amount on time, you may face rollover fees that compound quickly.
If you decide to use a connection service like FundingCashLoans, remember that the service is free and does not make credit decisions. You will be matched with independent third-party lenders, and any loan terms come directly from the lender. Review the terms carefully, including the APR, repayment schedule, and any fees. Consider whether a personal installment loan might be a better fit than a payday loan, as installment loans allow you to repay over a longer period. However, both types of loans should be used only as a last resort and only when you have a clear repayment plan.
After you have resolved the emergency, make rebuilding your emergency fund a top priority. Use the same strategies that helped you start: automate small transfers, bank windfalls, and cut back temporarily on non-essential spending. Each time you rebuild, you become more resilient and less reliant on borrowed money.
Staying Motivated on a Tight Budget
Saving on a tight budget can feel like a grind. It is easy to lose motivation when progress seems slow. To stay on track, focus on the why. An emergency fund buys you options. It means you can say no to a predatory loan, avoid late fees, and handle a crisis without panic. It means you can sleep at night knowing that a small financial shock will not derail your entire life.
Celebrate every milestone, no matter how small. Hit $100? Treat yourself to a small, free reward like a movie night at home. Hit $500? Share the news with a friend who supports your goals. The more you acknowledge your progress, the more your brain associates saving with positive feelings. Over time, saving becomes a habit rather than a chore.
Remember that building an emergency fund is a marathon, not a sprint. There will be months when you can save more and months when you can save less. That is okay. The important thing is to keep moving forward. Even $5 per week adds up to $260 in a year, and that could be the difference between a minor inconvenience and a financial crisis. Start where you are, use the tools available to you, and give yourself grace. Your future self will thank you.